
I. The Tower That Didn’t Need Height to Cast a Shadow
In my previous life, I walked by the CME towers every day. We lived in Greater Chicago then, and I worked at PwC in a tax specialty group called transfer pricing. I’d ride the train into Union Station, pass the CME towers, and cross the street to my office. They weren’t tall–they didn’t even crack Chicago’s top 100 tallest buildings–but symbolically, they stood at the center of the futures world.
CME’s own future is less clear.
CME has been the biggest player in the room for a century. And yet it’s now backing away from what is arguably the hottest opportunity in town: sports event contracts. As DeFI Rate recently reported, CME is ceasing to add sports and award markets, while letting existing ones trade out through expiration.
It’s a curious move that we covered in yesterday’s quick-hit podcast. In some ways, it’s not that surprising–Terry Duffy hasn’t actually vibed with the new guard–remember the middle finger?

But he also once acknowledged that sports could bring “a whole constituency that’s never been in [his] marketplace before.”
[Want more podcasts and videos like this? We have quite a few on our LexCurrent PM Reporter - free with registration for our Founding 250 members.]
That insight led to the CME–FanDuel partnership and the birth of FanDuel Predicts, which launched in late December 2025. CME framed it as a major expansion opportunity:
This launch is a pivotal step for expanding the reach of our products to FanDuel’s millions of registered users across the U.S.
And now the parents are divorcing.
II. The Divorce Papers Arrive
The split wasn’t shocking. Somewhere along the way, the relationship soured. In early August, Flutter announced that all Fanduel Predicts sports and novelty contracts would move to Crypto.com, leaving CME to handle only the financial-market contracts. That statement underestimates the imbalance: CME owned 51% of the exchange but only saw 1% of the volume. The father was paying child support but barely had visitation rights.
Now CME is formalizing the wind-down. They filed an amendment to the Listing Schedule of Sports and Cultural Related Event Contract Swaps (PDF). The divorce is official.
Let’s be clear here: CME is not exiting prediction markets entirely. Its broader event-contract business was growing rapidly before the sports retreat–Q2 average daily volume exceeded four million contracts, up roughly 40% quarter-over-quarter, with about 48 million contracts tied specifically to financial-market events. So, CME still competes with Kalshi and Polymarket.
And it’s not leaving sports entirely either. It’s exiting sports event contracts. CME still has FutureSports, a more traditional futures product that is based on sports performance (@CME - we have an even better one, but that’s a story for another day). So it still competes with Novig’s “Just Sports” exchange.
But the NFL is here, and sports event contracts are booming, and CME is walking away from the hottest game in town during a heatwave.
Why?
Two possibilities.
A. It’s Just Sports
Sports event contacts could have a multitude of meanings to DCMs:
For Novig, they are the business;
For Kalshi, they’re the predominant business; or
For CME, they’re a door to new traders.
CME doesn’t need sports event contracts–or prediction markets at all. In fact, CME has been here before. HedgeStreet, a tiny San Mateo outfit, became the first DCM specializing in event contracts back in 2004. In 2005, HedgeStreet’s total contract volume was $5 million; CME’s was $3 trillion, per day. David vs. Goliath. David didn’t win, but he survived–and forced a rematch. HedgeStreet eventually became Nadex, and is now under the Crypto.com umbrella. Nadex was the first DCM to self-certify sports event contracts (PDF). (Kalshi actually came soon after). Sports event contracts grew by leaps and bounds. CME realized sports could be a pathway into an intimidating corner of finance.
But CME is institutional. Retail traders don’t naturally gravitate toward it. CME lagged badly–it captured only 0.02% of total prediction-market volume in early July. And while CME hadn’t been named in any sports-contract litigation, the risk still existed. CME likely ran the calculus and determined the benefits did not outweigh the costs.
Plus CME already has a sports product. Perhaps part of the calculus included not competing against itself.

Maybe it really was just Sydney… I mean sports–a small, low-profit business that was easy to drop.
Yet…
B. It’s Not Just Sports
These perps...
Much has happened in this space, and words barely capture it. Let us offer you a visual instead:
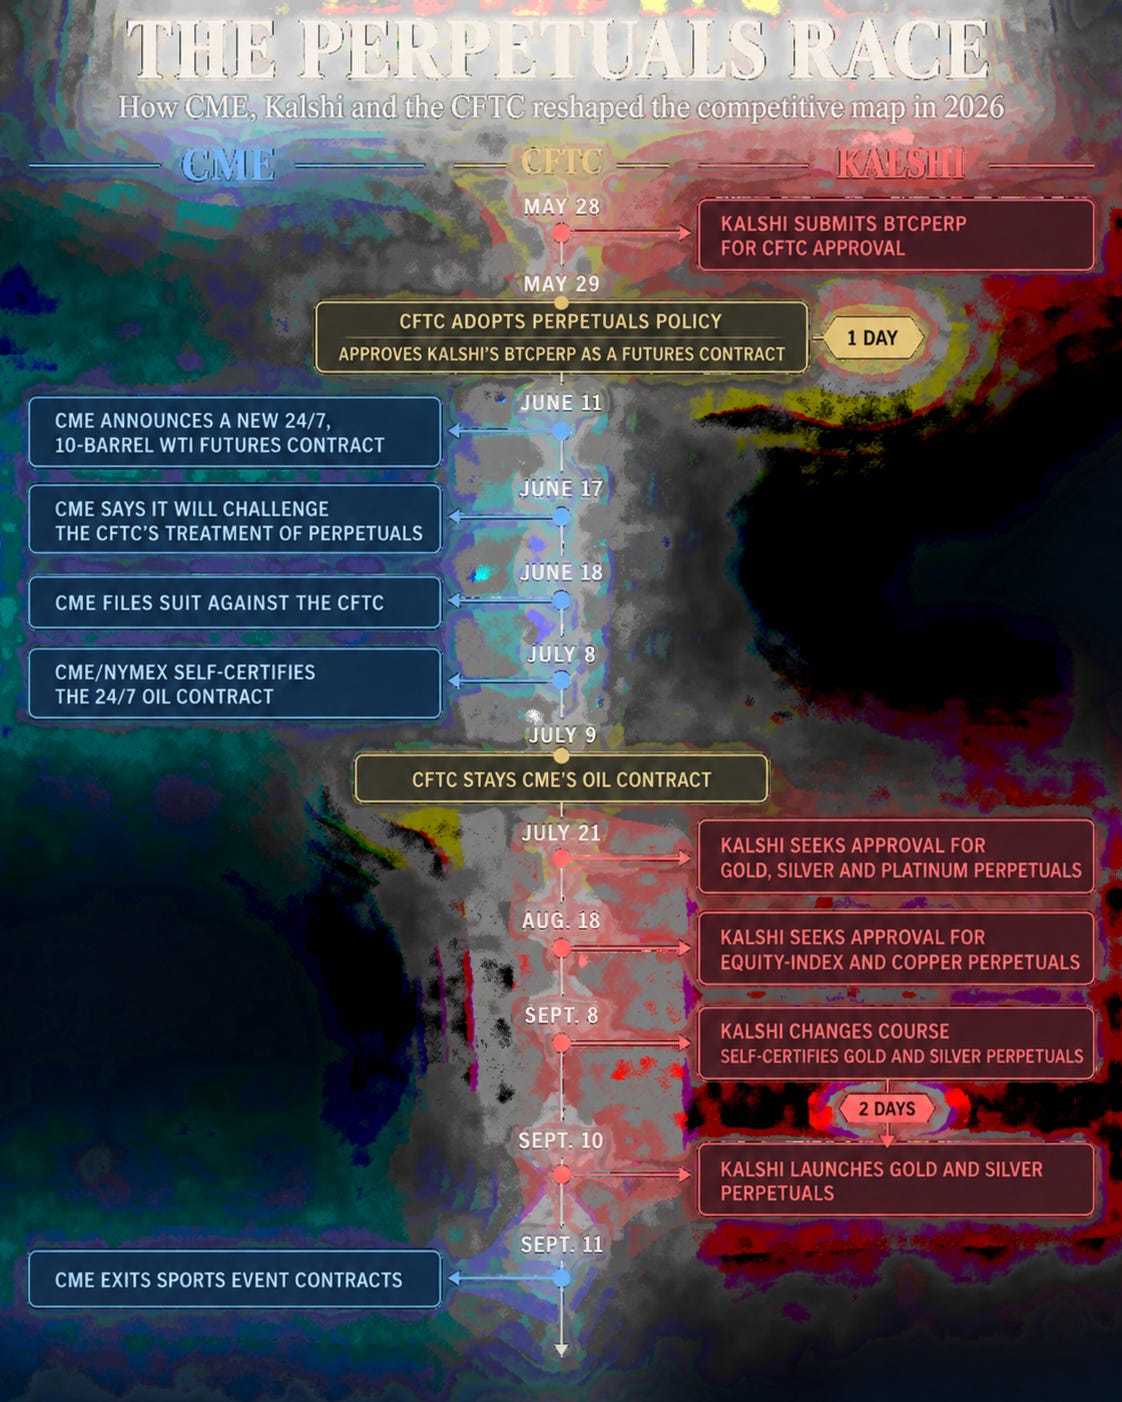
The gist: Kalshi submitted an application for Bitcoin perpetuals and got approved in one day. CME has a very different experience with its oil futures (amending the trading schedule to 24/7). Call it political favors if you want–the reality is Kalshi has shown it can disturb the big boy’s business at scale.
And that tiny event-contract outfit (HedgeStreet) that CME more or less ignored twenty years ago? Under Crypto.com, it’s flourishing–and it too can disturb the big boy’s business.
CME is now in court with the CFTC. It likely feels it has no choice. Meanwhile, Kalshi launched gold and silver perps (changing course and self-certifying, then launching in two days), and equity perps appear to be on the way.
From CME’s perspective, the threat isn’t sports event contracts growing at a massive rate. That’s inconvenient, but not existential. The more likely existential threat is sports becoming the beachhead for competitors to expand into other CME-related products.
This is no longer a game of checkers, it’s 3D chess.
III. The Long Memory of an Institution Built to Fight “Democratization”
Tarek Mansour grew up in Lebanon; Luana Lopes Lara is from Brazil. CME’s roots predate modern Lebanon–and, through the Chicago Board of Trade, the Brazilian republic. CME has been around for a very long time. It has seen everything.
CME became CME because it once beat back the bucket shops that came knocking on their doors:

Not that, the big boys were worried initially. The Board Of Trade’s official historian recalled they were viewed as (PDF):
…a sort of democratized Board of Trade, where the common people could speculate.
That “how cute” attitude was quickly squashed. The Board of Trade sued a bucket shop all the way to SCOTUS. Along the way, C. C. Christie, the Bucket Shop King, called the Board of Trade “the biggest bucket shop on Earth.”
But in the case of establishment vs. bucket shops, Justice Holmes delivered the lines that would shape modern futures:
As has appeared, the plaintiff’s chamber of commerce is, in the first place, a great market, where, through its eighteen hundred members, is transacted a large part of the grain and provision business of the world. Of course, in a modern market, contracts are not confined to sales for immediate delivery. People will endeavor to forecast the future, and to make agreements according to their prophecy. Speculation of this kind by competent men is the self-adjustment of society to the probable. Its value in well known as a means of avoiding or mitigating catastrophes, equalizing prices, and providing for periods of want. It is true that the success of the strong induces imitation by the weak, and that incompetent persons bring themselves to ruin by undertaking to speculate in their turn. But legislatures and courts generally have recognized that the natural evolutions of a complex society are to be touched only with a very cautious hand, and that such coarse attempts at a remedy for the waste incident to every social function as a simple prohibition and laws to stop its being are harmful and vain.
Speculation was fine– if organized. Democratization was a bridge too far. Bucket shops disappeared by 1915 (PDF) and CME went on to build an empire (PDF) on the idea that speculation is essential to price discovery and effective hedging.
Fast forward: Rob Schwartz (now partner at Morgan Lewis and my future co-panelist at PREDICT 2026) was litigating for the CFTC against Kalshi, and stated:
To build and maintain a thriving derivatives industry that is distinct from the gambling business has been the work of 175 years, and it’s important.
The math points directly to the founding of the Chicago Board of Trade in 1848. It secured the victory against the bucket shops in 1905 and eventually became part of the CME Group.
Gambling vs. futures is not a hoax. It’s the foundational narrative of CME’s existence.
And now that narrative is coming under fire.
Prediction-market CEOs are flipping the script: “If we are gambling, then I think you’re basically calling the entire financial market gambling,” declared Kalshi’s CEO, Tarek Mansour.
“Gambling is a type of behavior, not a type of product,” said Novig’s CEO Jacob Fortinsky.
Polymarket’s Shayne Coplan didn’t even bother with those parallels, describing its exchange as: “a site where you can basically bet on current events.”
And so far, it’s working.
IV. The Real Reason CME Walked Away
CME is not just losing business.
It’s losing the narrative.
And if it loses the narrative, it could lose the entire business.
CME has to be the responsible adult in the room; it has no other choice. And it cannot credibly defend the futures industry’s legitimacy while simultaneously profiting on sports event contracts.
But the stakes extend well beyond sports. If CME cannot define—and defend—the boundaries of the futures business, it may not have much of a future.